Hail damage on your roof? How to spot it, and how the claim works in Michigan.
What hail damage looks like, what size hail causes it, what your policy will and will not pay, and how to pick a roofer.
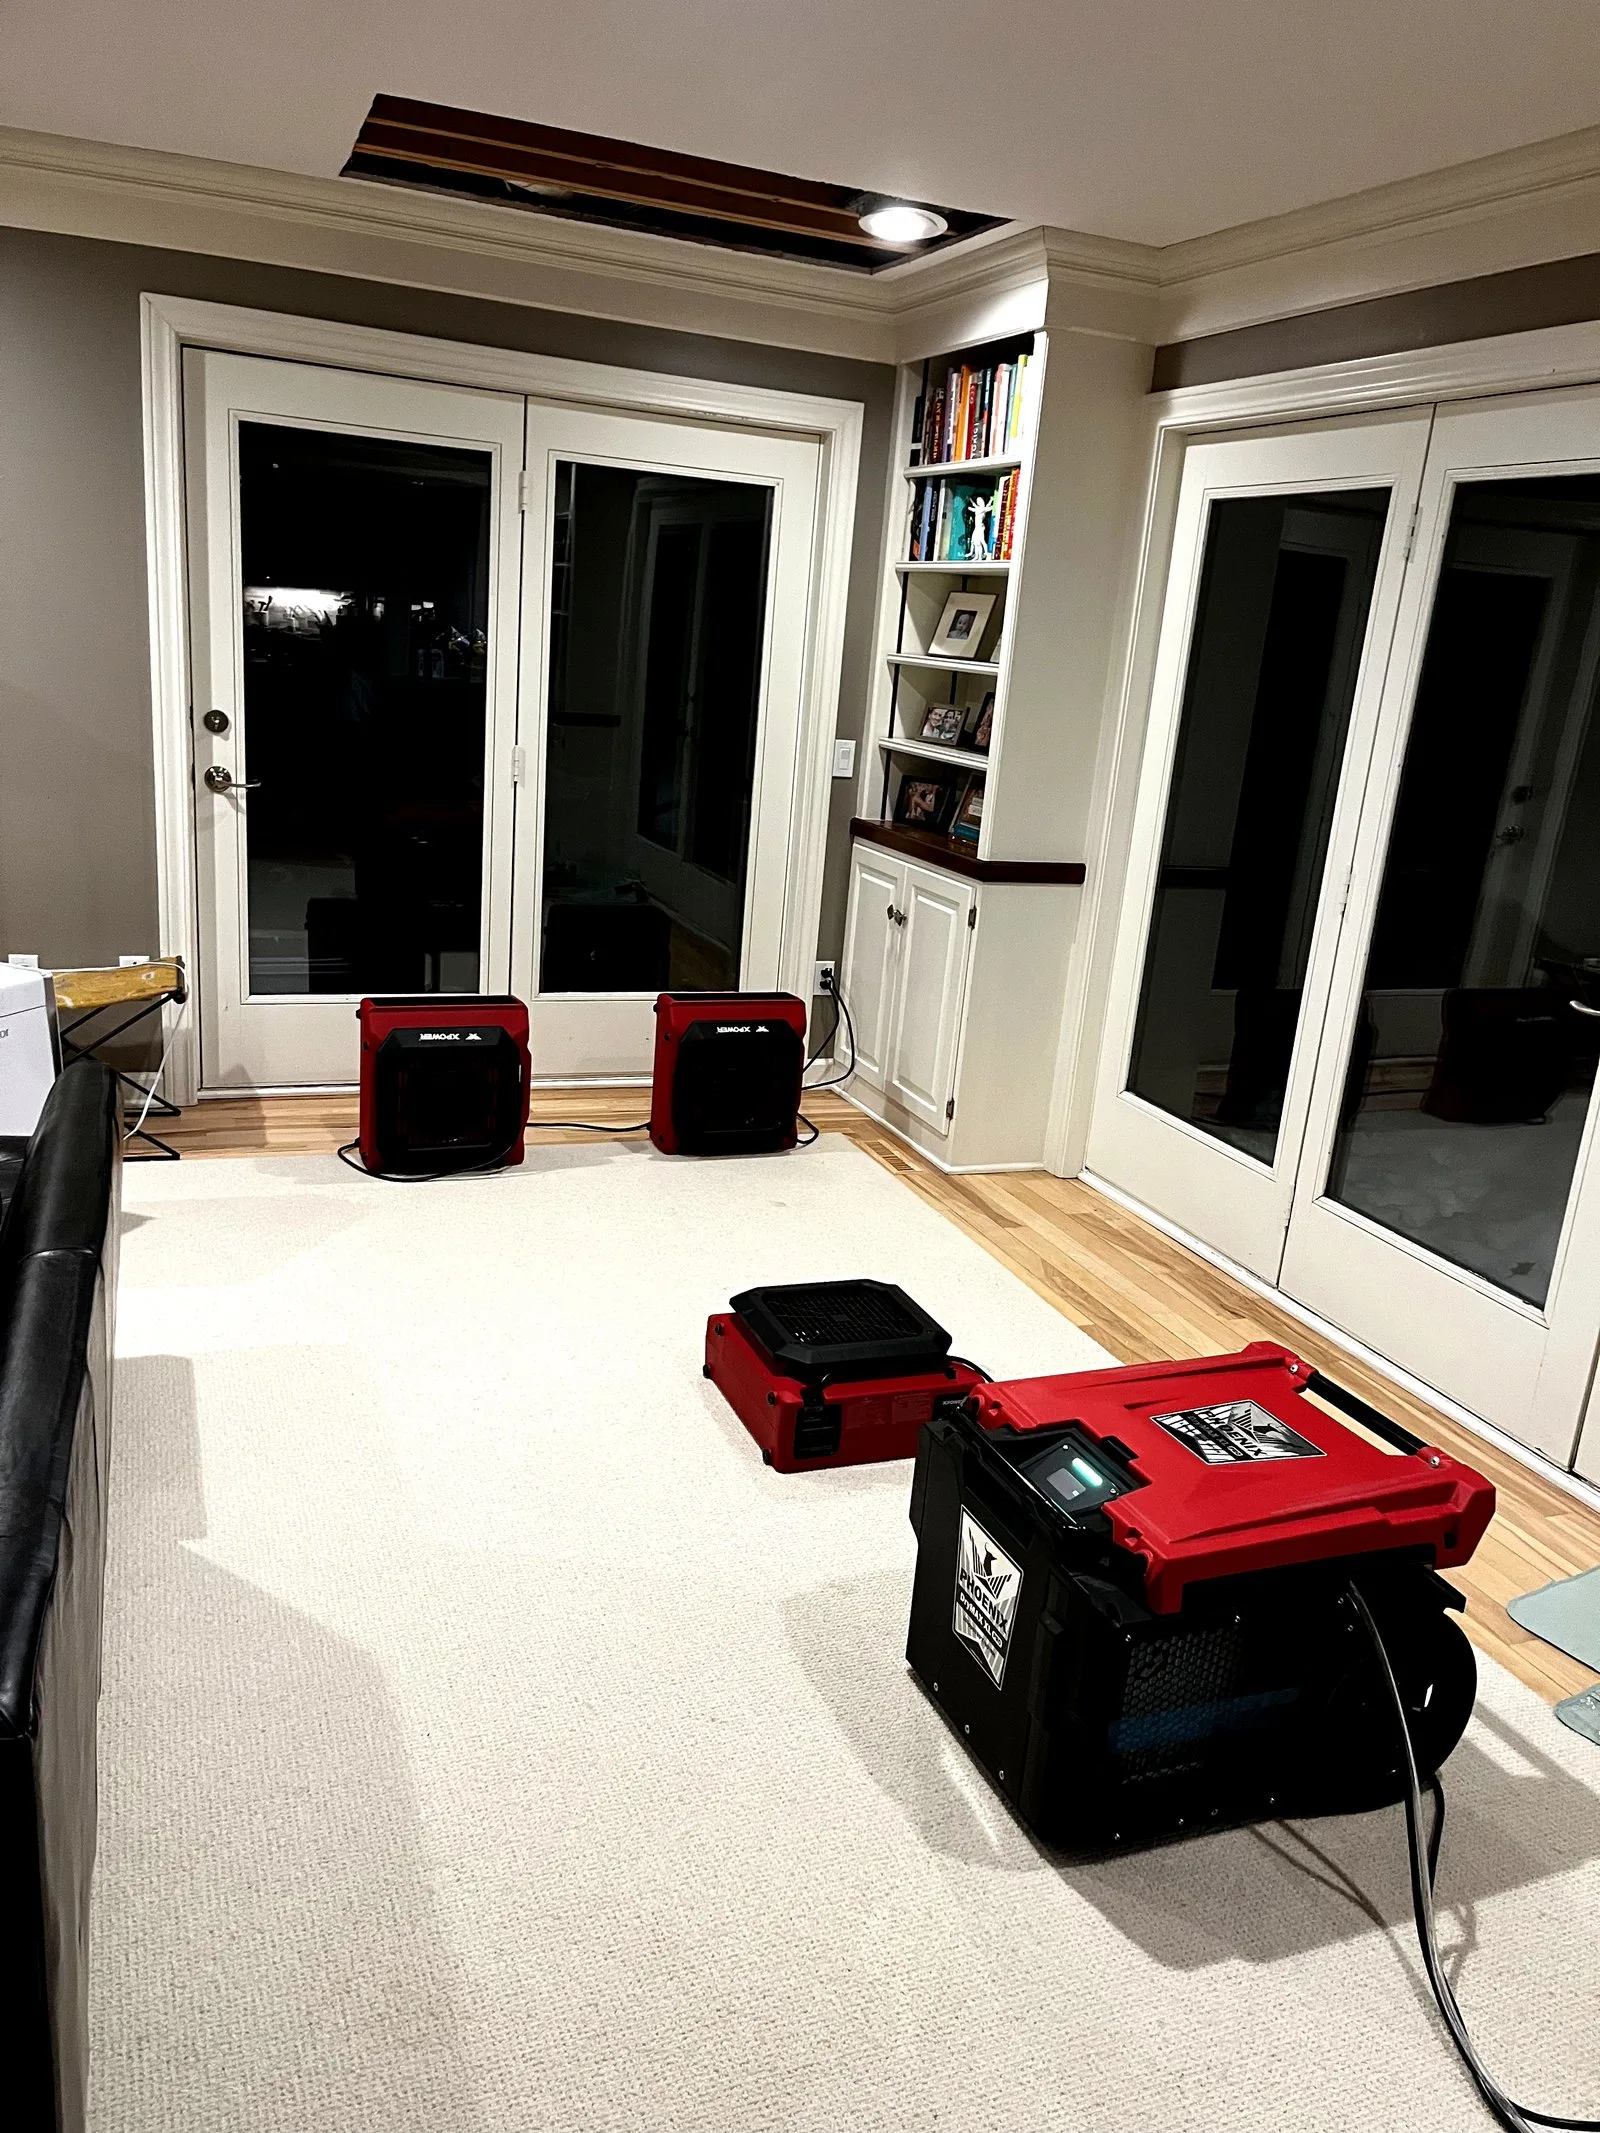 Drying equipment in a room after part of the ceiling was opened up.
Check from the ground first: dents or spatter marks on the air conditioner, gutters and downspouts show hail fell. On the roof, hail leaves a random pattern of dark hits, lost granules and soft, bruised spots. Hail about 1 inch across or larger is the size that usually damages shingles. If you find damage, tell your insurer as soon as possible, cover any openings, take photos, and do not make permanent repairs until the insurer has inspected. In Michigan the policy pays for the damaged part of the roof; the insurer does not have to replace the whole roof.
After a hailstorm, two questions usually come up: did it actually damage my roof, and is it worth an insurance claim? This guide answers both, with what Michigan homeowners need to know about deductibles, depreciation and hiring a roofer.
Our sources are Michigan’s insurance department (DIFS) and licensing department (LARA), NOAA, the Insurance Institute for Business & Home Safety (IBHS), the national association of insurance regulators (NAIC), the Insurance Information Institute, Travelers, and Nebraska’s insurance department, whose hail guide goes into more detail than Michigan’s. We are a restoration company: we tarp damaged roofs and dry out water that gets inside.
What size hail damages a roof?
NOAA’s National Severe Storms Laboratory counts hail of 1 inch across (quarter size) or larger as severe. Its size guide: 3/4 inch is penny size, 1 inch quarter, 1½ inches ping-pong ball, 1¾ inches golf ball, 2½ inches tennis ball. It says measuring a stone with a ruler is better than comparing it to an object.
Nebraska’s Department of Insurance gives this rough guide for shingles:
- Heavier asphalt shingles and wood shakes generally need hail about 1¼ inches across before they are damaged.
- Lightweight asphalt shingles may show damage from 1-inch hail.
- Hail under 1 inch normally only damages shingles that are already worn.
Small hail still matters over time. IBHS research found that hail under 1 inch, which falls far more often, knocks protective granules off asphalt shingles and speeds up their aging. In its tests, weathered shingles hit by two rounds of small hail became up to ten times more likely to be damaged by a later large hailstorm than new shingles.
Size is not the only factor. Travelers lists wind speed and direction, how dense the hailstones are, the roofing material, the roof’s age and condition, and shelter from trees, fences or neighboring houses.
A note on coin names: NOAA calls 3/4 inch penny size, while Nebraska’s guide calls it dime size. Go by inches.
How to tell if your roof has hail damage
1. Look at ground level first
IBHS says to start with collateral damage: spatter marks or dents on the air conditioner, gutters, metal flashing, downspouts or patio furniture. These confirm a hail event happened, which helps separate hail damage from normal wear. Nebraska’s guide adds that hail strong enough to damage a roof also marks nearby cars, wood fences, shutters and siding. A pile of shingle granules at the bottom of a downspout may be a sign of damage, but it does not prove it.
2. Know what hail damage looks like on shingles
From IBHS and Travelers, signs of hail on asphalt shingles are:
- Impact marks in a random pattern, with no order to them.
- Hits that look black, where granules have been knocked off and the layer underneath shows. The exposed asphalt or mat can look shiny.
- Soft spots you can feel when you press, like the bruise on an apple.
- Cracks or breaks where the hail struck. IBHS notes that ridge caps are especially vulnerable.
On wood shingles, Travelers says to look for random splits that are brown or orange with sharp corners and edges, and dents along the splits.
Bigger hits matter more. In IBHS leak testing, small dents let in very little water, but large dents and tears let in a lot.
3. Rule out the look-alikes
Not every missing granule is hail. IBHS, Travelers and Nebraska’s guide all list damage that is often mistaken for it:
- Granule loss along the edges of shingles, or even wear across the roof, from normal aging. Heavy rain can knock granules off too.
- Curled or cupped edges, fine random “craze” cracks, and cracks from shrinking asphalt as shingles harden with age.
- Blisters that have popped. Nebraska notes these do not have the bruise you can feel at a hail hit.
- Green, brown, orange or gray streaks from algae or lichen.
- A diagonal pattern of wear across the roof, which usually points to a manufacturing defect.
- Rounded or horseshoe-shaped marks, often near the ridge, from hammers or tools, not hail.
Nebraska’s rule of thumb: hail leaves a random pattern of marks in different sizes. If the damage has a pattern, hail probably did not cause it.
You can check most of this from the ground. Before you decide whether to claim, have a licensed roofer look at the roof itself.
Find the date and size of the storm
Your insurer will want to know when the storm happened. Two free NOAA records help:
- Storm Prediction Center storm reports: a page for each day listing hail reports with the size, location and time. The reports are preliminary, and they go back to June 1999.
- The NCEI Storm Events Database: the official National Weather Service storm record, searchable by state or on a map. It lags behind by a few months; in November 2026 it ran to July 2026.
Write down the date, and keep your own photos of hailstones next to a ruler if you have them.
Is hail damage covered by homeowners insurance in Michigan?
Usually. DIFS says most homeowners policies cover many types of wind and hail damage, but coverage varies by policy. The Insurance Information Institute says standard homeowners insurance covers wind and hail. The NAIC notes that some policies exclude wind and hail, mostly in coastal areas, so it is worth confirming yours.
One Michigan point is worth knowing before you file. DIFS says that if hail and high winds lift shingles off your roof, a homeowners policy only covers the portion of the roof that was damaged, and the insurance company is not required to replace the entire roof. Whether the adjuster recommends repair or replacement depends on how much damage there is.
What you will actually be paid: deductibles and depreciation
Your deductible
Your deductible is on the declarations page of your policy. The Insurance Information Institute explains that it can be a dollar amount or a percentage of the amount your home is insured for. With a 2% deductible on a home insured for $100,000, $2,000 comes off the claim.
Some policies have a separate wind and hail deductible. The Institute says these are usually percentages, typically 1% to 5%, and most common in Midwestern states like Ohio and around Tornado Alley. It does not name Michigan, so check your own declarations page. The NAIC adds that some policies have special deductibles for parts of the home, like the roof.
Replacement cost or actual cash value
The NAIC explains the difference:
- Replacement cost value (RCV): pays the cost to repair or replace the damage without taking off depreciation.
- Actual cash value (ACV): pays the depreciated cost, based on the roof’s condition, what new would cost and how long it would normally last.
Its example: two families each have $15,000 of roof damage and a $1,000 deductible. The family with replacement cost coverage is paid $14,000. The family with actual cash value coverage has $10,000 taken off for depreciation and is paid $4,000.
Even with replacement cost coverage, the money often comes in two parts. Nebraska’s insurance department says the insurer usually pays the actual cash value minus your deductible first, then the difference after the repairs are done, within a time limit set by the policy, often 180 days. Check the time limit in yours.
Is it worth filing a hail claim?
Nebraska’s insurance department gives two things to weigh:
- If the repair will cost less than your deductible, consider not filing.
- Some insurers look at wind and hail claims when deciding whether to renew a policy, even when nothing was paid out.
A written estimate from a licensed roofer, compared with your deductible, usually answers the question.
Hail opened your roof, or water is coming in?
We tarp damaged roofs, board up broken windows and dry out water that gets inside, 24/7 across Kent and Ottawa County. We are there in under 60 minutes on most calls. We write our estimates in Xactimate and bill your insurer directly.
(616) 822-1978How to file a hail claim in Michigan, step by step
These steps follow DIFS’s guide to filing a claim after a disaster, with two additions from Nebraska’s regulator.
- Tell your insurer or agent as soon as possible. Keep notes of every call: date and time, the claim representative’s name, your claim number and what was said. DIFS has a free claim tracking sheet.
- Stop further damage. Most policies require reasonable steps, such as tarping a damaged roof or boarding up broken windows. Keep the receipts; these costs may be reimbursed.
- Document everything. Take photos and video of all damage before cleaning up. Nebraska suggests a written list of everything else that looks damaged, like windows, shutters, siding, fascia, ceilings and satellite dishes, for the adjuster.
- Hold off on permanent repairs until your insurer has inspected the damage or tells you to go ahead.
- Compare estimates. If roofers’ estimates come in higher than the adjuster’s, Nebraska says to tell the adjuster; there may be differences in materials or damage they can explain or resolve.
- If you disagree, talk to the insurance company first. If you believe the claim was not handled properly, you can file a complaint with DIFS at 877-999-6442.
Two more points from DIFS: there is no set time limit for the insurer to finish investigating, so stay in touch, and if the wait seems unreasonable you can complain to DIFS. And if water came inside, describe it as water damage rather than “flooding”, because flood has a special meaning in insurance and may not be covered.
Public adjusters. You can hire one to represent you, but you do not have to. In Michigan they must be licensed by DIFS and their fee cannot be more than 10% of the settlement.
Choosing a roofer after a hailstorm
DIFS warns that disasters often attract scammers. Michigan’s rules help protect you:
- It is your choice. DIFS says your insurer may recommend contractors, but you have the right to hire the contractor you want.
- Check the license. LARA says anyone doing work worth $600 or more in labor and materials must be licensed. Roofing is one of the trades on a Maintenance and Alteration license. Ask to see the pocket card, or check LARA’s license database or call 517-241-9309. IBHS also suggests a roofer who is bonded and insured and has a local address.
- Get several written estimates with the total price, payment terms, materials and expected time. LARA warns about “special prices” for leftover materials or because of other jobs in the neighborhood.
- Never pay the whole job up front. LARA suggests a deposit when work starts and payments as it progresses, by check to the company name. DIFS lists full payment up front, high pressure, unsolicited door-to-door offers and asking you to sign insurance checks over to a contractor as warning signs.
- Permits. Michigan’s building code requires a permit for roofing work, according to Muskegon Charter Township’s 2025 roofing handout, and LARA says the contract should state that the contractor will get all permits.
- Three days to cancel. If a contractor came to you and you signed at home, LARA says you have three days to cancel by registered letter.
The same Muskegon handout summarizes code items for re-roofing: an ice barrier from the eave edge to at least 24 inches inside the exterior wall, and no reuse of rusted, damaged or deteriorated vent flashing or metal edging. It is worth asking whether your estimate includes them.
If you are replacing the roof anyway, IBHS suggests shingles rated “Good” or “Excellent” in its impact-resistance ratings.
Frequently Asked Questions
Does homeowners insurance cover hail damage to a roof in Michigan?
Usually, but check your policy. Michigan’s Department of Insurance and Financial Services (DIFS) says most homeowners policies cover many types of wind and hail damage, but coverage varies by policy. Look at your declarations page for your deductible and whether hail has its own deductible.
How do I know if my roof has hail damage?
Start on the ground: dents or spatter marks on the air conditioner, gutters, downspouts, metal flashing or patio furniture show that hail fell. On the shingles, hail leaves a random pattern of dark impact marks, lost granules, cracks, and soft “bruised” spots you can feel when you press. Normal wear, blisters and manufacturing defects can look similar, so have a licensed roofer check before you decide.
What size hail damages a roof?
The National Weather Service treats hail of 1 inch (quarter size) or larger as severe. Nebraska’s insurance department says lightweight asphalt shingles may show damage from 1-inch hail, heavier shingles and wood shakes usually need about 1¼ inches, and hail under 1 inch normally only damages shingles that are already worn. IBHS research adds that repeated small hail wears shingles down faster.
Will insurance replace my whole roof after hail?
Not necessarily. DIFS says that if hail and high winds lift shingles off your roof, a homeowners policy only covers the portion of the roof that was damaged, and the insurer is not required to replace the entire roof. Whether the adjuster recommends repair or replacement depends on how much damage there is.
How much will insurance pay for hail damage?
It depends on the damage, your deductible and your type of coverage. With replacement cost coverage you are paid the cost to repair or replace without depreciation, though the money may come in two payments. With actual cash value coverage, depreciation is taken off. In an NAIC example, the same $15,000 roof damage with a $1,000 deductible paid $14,000 under replacement cost and $4,000 under actual cash value.
Is it worth filing a claim for hail damage?
Not always. Nebraska’s insurance department says that if repairs will cost less than your deductible, consider not filing, and that some insurers count wind and hail claims when deciding whether to renew a policy, even when nothing was paid. Getting a roofer’s estimate first helps you decide.
What should I tell the insurance adjuster?
Stick to what happened and what you can show: the storm date, your photos, and a written list of everything that looks damaged. If water came inside, DIFS suggests describing it as water damage rather than “flooding”, because flood has a special meaning in insurance. If roofers’ estimates come in higher than the adjuster’s, tell the adjuster.
How long do I have to file a hail claim in Michigan?
Your policy sets the deadlines, so read it. DIFS says to notify your insurance company or agent as soon as possible. Replacement cost policies also usually give you a limited time to finish repairs before the rest of the money is paid; Nebraska’s insurance department says this is often 180 days.
Does a roofer need a license in Michigan?
Yes, for jobs of $600 or more in labor and materials. Michigan’s Department of Licensing and Regulatory Affairs (LARA) says roofing is one of the trades on a Maintenance and Alteration contractor license. Licensed contractors carry a pocket card, and you can check a license online or by calling 517-241-9309.
Do I have to use the contractor my insurance company recommends?
No. DIFS says your insurance company may recommend contractors, but you have the right to hire the contractor of your choice.